
In 800 VDC AI data centers, capacitors do not disappear from the power chain.
They move into higher-voltage, higher-temperature, higher-frequency and energy-storage positions. A new MarketEYE analysis by Dennis M. Zogbi of Paumanok Publications maps where that content sits and which dielectrics gain or lose ahead of volume deployment in 2027.
Why AI racks are moving to 800 VDC
For about three decades, data centers have been powered the same way. Utility AC passes through transformers, switchgear and UPS systems, is converted several times, and is finally stepped down to the 54 V, 12 V and sub-1 V rails that feed AI processors. Each conversion point carries its own capacitor bill of materials.
That model is now under strain. Power per AI rack has grown from tens of kilowatts to well over 100 kW, and the industry is planning for racks above 1 MW. At those levels, low-voltage distribution inside the rack is no longer practical.
The current argument in numbers
At fixed power, current falls as voltage rises. A 1 MW rack fed at 54 V needs roughly 18,500 A; at 800 V it needs about 1,250 A.
| Bus voltage | Current at 1 MW | Relative conduction loss* |
|---|---|---|
| 54 V DC | ≈ 18,500 A | 1 |
| 800 V DC | ≈ 1,250 A | ≈ 1/220 |
*Same conductor resistance; conduction loss scales with the square of current.
NVIDIA estimates that 800 VDC reduces copper by 45% compared with 415 V AC distribution, carries 85% more power through the same conductor size, improves end-to-end efficiency by up to 5% versus 54 V systems and lowers maintenance costs by up to 70%.
Timeline of the transition
- May 2025: NVIDIA commits to 1 MW IT racks from 2027, with full-scale 800 VDC production aligned with its Kyber rack-scale systems. Named partners include Infineon, Texas Instruments, STMicroelectronics, onsemi, ROHM, Navitas, Delta, LiteOn, Eaton, Schneider Electric and Vertiv.
- March 2026: NVIDIA, Google and Microsoft publish an 800 VDC white paper through the Open Compute Project. Texas Instruments introduces a complete 800 V reference architecture, from hot-swap protection at the rack input to the multiphase converters feeding the GPU core.
- July 2026: Version 0.3 of a low-voltage DC solid-state transformer specification is released.
- August 2026: NVIDIA schedules its first MGX-compatible 800 VDC power rack for the second half of 2026, with row power centers of up to 2 MW per rack row in 2027. More than 80 companies are building to the specification.
Where capacitors sit in the 800 VDC power chain
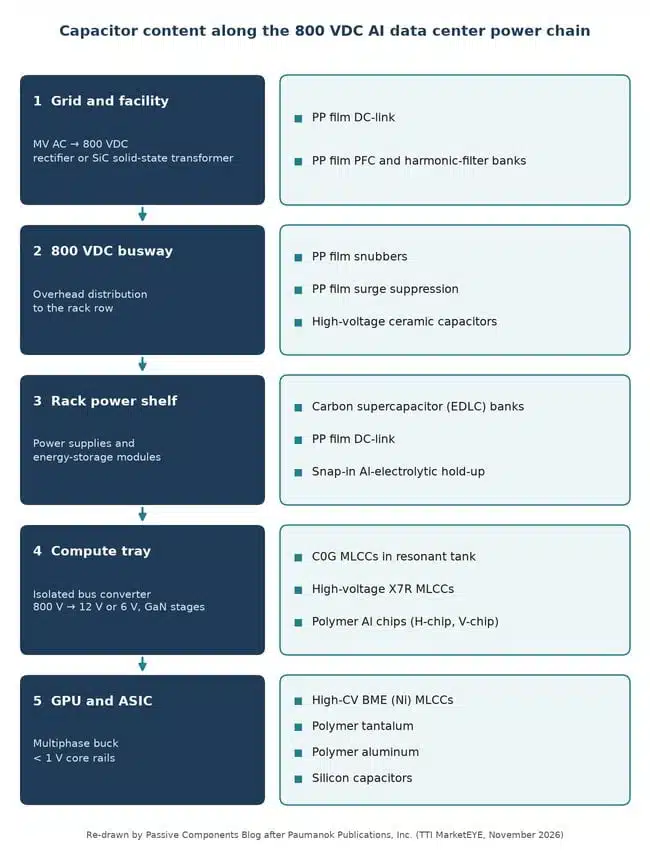
The power chain can be divided into five stages, each with a distinct capacitor profile.
Grid and facility
Medium-voltage AC is converted to 800 VDC by a rectifier or, increasingly, a silicon-carbide solid-state transformer. This stage uses polypropylene film DC-link capacitors and film capacitor banks for power-factor correction and harmonic filtering.
800 VDC busway
Overhead distribution to the rack row carries modest but demanding capacitor content: polypropylene film snubbers, polypropylene surge suppression, and high-voltage ceramic chip and through-hole capacitors.
Rack power shelf
Power supplies and energy-storage modules sit here. This is where new demand for carbon supercapacitor banks appears, alongside polypropylene film DC-link capacitors and snap-mount aluminum electrolytic hold-up capacitors.
Compute tray
An isolated bus converter steps 800 V down to 12 V or 6 V, increasingly with gallium-nitride power stages. These converters rely on C0G ceramic capacitors in the resonant tank, high-voltage X7R MLCCs and conductive polymer aluminum chips.
GPU and ASIC
Multiphase buck converters deliver less than 1 V to the processor core. This remains the domain of high-capacitance BME (nickel-electrode) MLCCs, polymer tantalum and polymer aluminum capacitors and, increasingly, silicon capacitors.
Polypropylene film: the DC-link winner
The metallized polypropylene film capacitor is the largest single beneficiary of the transition. Polypropylene film capacitors are self-healing, have very low dielectric losses, handle high ripple current and reach voltage ratings well above 800 V in a single winding. These are the properties a DC-link needs: it sits between the rectifier and the downstream converter, absorbs transient energy and keeps the bus voltage stable.
Film appears at every high-voltage stage: at the rectifier or solid-state transformer output, inside the rack power shelf, in busway snubbers and surge modules, and in campus-level PFC and harmonic-filter banks. SiC and GaN switching raises ripple-current density in the DC-link, which further favors film.
Temperature is the constraint
Standard polypropylene film capacitors are typically rated to 85 °C, with a maximum of 105 °C. Power stages in AI busways and racks may reach 125 °C to 135 °C. That gap drives demand for higher-temperature film dielectrics and is an opportunity for vendors able to qualify them.
In practice, polypropylene film also requires voltage derating as temperature rises toward its upper limit, so hot-spot temperature, ripple-current self-heating and the required voltage margin must be evaluated together when sizing an 800 V DC-link.
Film supply concentration
Capacitor-grade polypropylene resin and the ultra-thin biaxially oriented film made from it come from a small number of producers. AI data centers now compete for the same capacity as EV inverters, solar and wind inverters and HVDC transmission.
Aluminum electrolytic: displaced at the bus, expanding at the board
A single liquid-electrolyte aluminum capacitor is practical up to roughly 450 V to 550 V. An 800 V bus therefore requires series stacks with balancing resistors, adding cost, board area and failure points. Film is consequently likely to take over the 800 V DC-link position that snap-in and large-can aluminum capacitors have traditionally held in industrial drives and UPS systems.
The picture is not one-directional:
- Snap-mount and large-can aluminum capacitors remain essential for hold-up and bulk capacitance wherever intermediate bus voltages fall within their ratings.
- The large installed base of AC-fed AI racks will continue to be built and serviced for years.
- On the low-voltage side of the bus converter, the 800 V architecture increases the number and value of conductive polymer aluminum capacitors (H-chip, V-chip and some radial designs) on the compute tray and accelerator board.
Lead times for polymer aluminum chips of 28 to 31 weeks show how tight that supply already is.
Ceramic capacitors: higher voltage and higher frequency
The isolated bus converter is where MLCCs gain the most. Texas Instruments’ 800 V to 6 V bus converter with integrated GaN power stages reaches 97.6% peak efficiency and a power density above 2,000 W/in³. Converters of this density switch at high frequency, and their resonant tanks require C0G (NP0) capacitors, which hold capacitance across temperature and voltage and have very low losses.
The same converters need high-voltage X7R MLCCs for input filtering and snubbing at 800 V, often stacked or in large case sizes. Because class 2 dielectrics lose a significant share of capacitance under DC bias, effective capacitance at the working voltage, not nominal capacitance, should drive part count and case-size decisions.
High-voltage, high-reliability MLCCs are not commodity parts. Their vendor base is far narrower than for general-purpose chips, and many use palladium-silver internal electrodes. At the processor, the 6 V to sub-1 V stage keeps the very large count of high-capacitance BME decoupling MLCCs that have defined AI server boards since 2023.
Supercapacitors: energy storage returns to the rack
The 800 V architecture brings energy storage directly into the rack. AI training workloads make GPU power draw swing sharply within fractions of a second, and those swings propagate back to the utility. NVIDIA includes energy storage in the 800 VDC architecture specifically to absorb load spikes and sub-second power swings.
Electric double-layer capacitors (EDLCs) suit this role because they deliver and absorb power quickly over hundreds of thousands of cycles. Texas Instruments’ reference architecture includes 800 V capacitor bank units built from EDLC cells, with a power density of 40 W/in³.
With individual EDLC cells typically rated around 2.7 V to 3 V, an 800 V bank implies roughly 270 to 300 cells in series. Cell voltage balancing, cell-to-cell capacitance and leakage spread, and thermal ageing therefore become central design issues.
For an industry that has relied on niche markets such as wind-turbine pitch control, transport boost power and memory hold-up, the AI rack could become the first truly high-volume application. That would put new demand on high-purity activated carbon electrodes and organic electrolytes.
Polymer tantalum at the point of load
Polymer tantalum capacitors keep their role at the point of load, alongside polymer aluminum chips, where low ESR, volumetric efficiency and a benign failure mode matter. Higher power per rack increases the number of point-of-load converters and the tantalum and aluminum polymer capacitance they require.
Impact by passive component family
| Component family | Role in 800 VDC architecture | Paumanok outlook |
|---|---|---|
| Polypropylene film | DC-link, snubbers, PFC and harmonic filters | Strong gain; high-temperature film is the key opportunity |
| Aluminum electrolytic (snap-in, large can) | Hold-up, bulk capacitance, legacy DC-link | Mixed; displaced at 800 V DC-link, supported by AC installed base |
| Polymer aluminum (H-chip, V-chip) | Compute tray and accelerator board | Strong gain; ~10% annual growth for H-chips to 2031 |
| High-voltage and C0G MLCCs | Resonant tanks, input filters, snubbers | Strong gain; narrow vendor base supports pricing |
| High-CV MLCCs | GPU and ASIC decoupling | Steady gain with rack power |
| Supercapacitors (EDLC) | Rack energy storage for GPU load swings | New high-volume market |
| Polymer tantalum | Point-of-load conversion | Steady |
| Resistors | Balancing, precharge, current sense | Gain in high-voltage types |
| Inductors and transformers | Bus converters, facility conversion | Shift to planar and high-frequency ferrite |
Materials and supply chain implications
Demand moves toward polypropylene resin and film, high-voltage etched and formed aluminum anode foil, activated carbon for supercapacitors, and the nickel, silver and palladium used in ceramic capacitors. Several of these materials markets are already tight, and the AI power build-out adds a further source of demand.
Paumanok expects the following product groups to capture a larger share of new power-conversion content as 800 VDC designs enter volume production:
- Polypropylene film capacitors in large-can, interference-suppression and snubber designs
- Snap-mount and large-can aluminum electrolytic capacitors where bus voltages permit
- High-voltage C0G MLCCs with palladium-silver electrodes
- High-capacitance BME MLCCs for decoupling
- Solid polymer tantalum capacitors
- Carbon supercapacitors
Design and sourcing notes
- Treat the 800 V DC-link as a thermal problem as much as a voltage problem; check film temperature class and voltage derating against realistic hot-spot conditions of 125 °C and above.
- Avoid series-stacked aluminum electrolytics on the 800 V bus where a single film part meets the requirement; where stacks remain, include balancing-resistor losses in the thermal budget.
- Size high-voltage X7R input and snubber capacitors on effective capacitance at operating voltage and temperature.
- Plan supercapacitor banks with active balancing and end-of-life capacitance and ESR margins.
- Qualify second sources early for high-voltage MLCCs, high-temperature film and polymer aluminum chips, where vendor bases are narrow and lead times are already long.
Conclusion
800 VDC distribution is becoming the standard for AI racks of 1 MW and above, with first products in late 2026 and volume deployment from 2027. Polypropylene film is the clearest winner at the DC-link, constrained by high-temperature performance and concentrated film supply. Aluminum electrolytics lose the 800 V DC-link but gain polymer chip content on the board, while high-voltage and C0G MLCCs, supercapacitors and high-voltage resistors emerge as new growth markets. For manufacturers, materials suppliers and buyers, the transition is a reason to revisit capacity and sourcing plans for film, high-voltage ceramics, aluminum, tantalum and EDLC cells.
Further reading
- AI Hardware Demand for Passive Components Dossier
- Enabling the 800 V AI Server Era: How C0G High-Voltage MLCC Supports Next-Generation Power Architectures
- Samsung MLCC Options for 1 MW AI Rack Power
- Advanced Electronics Markets Reshape Capacitor Demand for 2026/2027
Source
This article is based on a MarketEYE analysis by Dennis M. Zogbi of Paumanok Publications, Inc., published by TTI on November 5, 2026. Market outlooks and forecasts reflect Paumanok’s analysis; current-scaling figures and design and sourcing notes are editorial additions.